Policy rate: what does holding at 2.25% mean for buyers?
Frédéric Vinet, real estate broker
On July 15, 2026, the Bank of Canada held its policy rate at 2.25%. For buyers, prime rates and variable mortgage rates should therefore stay fairly stable, which helps when planning a purchase. Fixed rates depend more on the bond market. Waiting for a cut isn't necessarily the best strategy: a cut could bring buyers back to the market and push up competition and prices.
On July 15, 2026, the Bank of Canada announced it was holding its policy rate at 2.25%, where it has been since December 2025.
For buyers, the decision brings some stability. A steady policy rate means the prime rates at financial institutions and variable mortgage rates should stay fairly stable, which can make it easier to plan a purchase.
It's worth separating the policy rate from mortgage rates, though. Variable rates are more directly affected by the Bank of Canada's decisions, while fixed rates depend largely on conditions in the bond market.
Is this the right time to buy?
Even though plenty of buyers are waiting for rates to drop before they act, that isn't necessarily the best strategy.
A cut to the policy rate could bring more buyers back to the real estate market. Higher demand could then increase competition and put upward pressure on property prices.
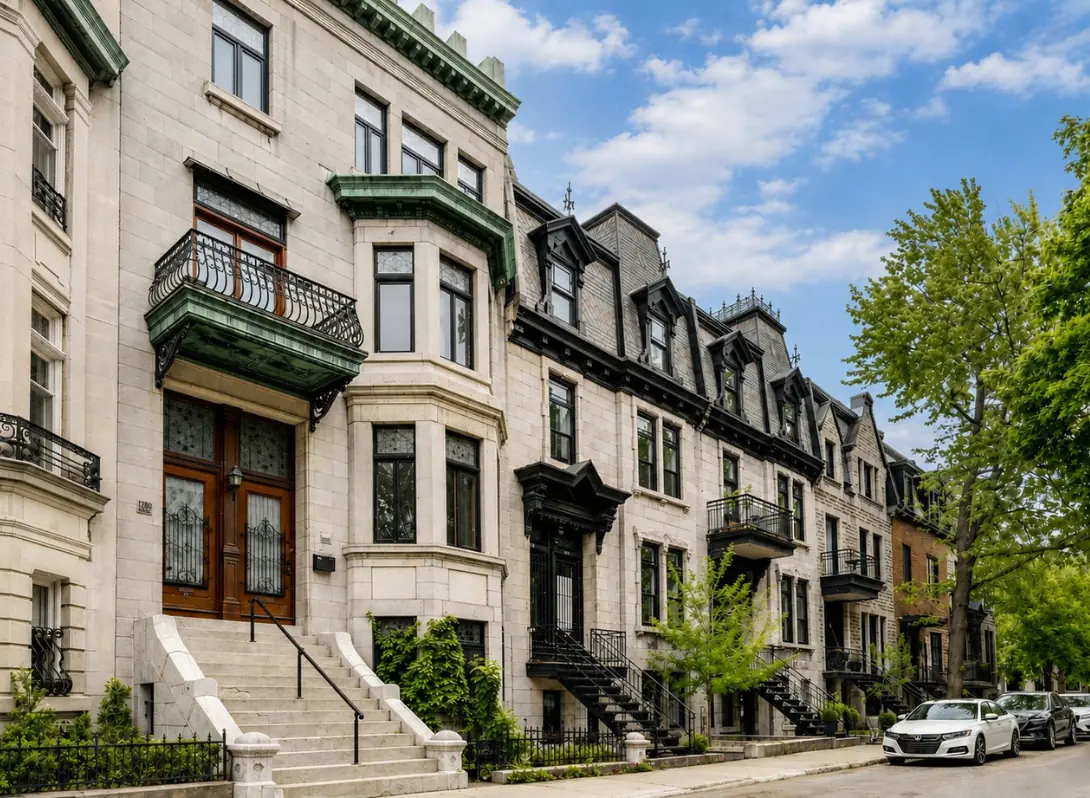
In Montréal, the effect can also vary from one area to another. A buyer looking for a condo on the Plateau-Mont-Royal, a house in Rosemont–La Petite-Patrie or a property in Outremont has to weigh mortgage rates, property prices and the inventory available in that area all together.
Rather than waiting for the “perfect moment,” it usually makes more sense to ask whether your finances let you buy now and whether the property really fits your budget and your needs.
What does it mean for buyers and sellers?
Holding the policy rate at 2.25% gives the real estate market a fairly predictable backdrop for now.
For buyers, it makes financing costs and mortgage payments easier to plan. For sellers, where rates go can also affect how many buyers are active on the market and how much they can afford.
The coming months could be worth watching for anyone looking to buy or sell a property in Montréal.
The Bank of Canada's next announcements are scheduled for September 2, October 28 and December 9, 2026. Buyers, sellers and real estate professionals will be following them closely, since they could affect where mortgage rates, demand and the real estate market go next.
If you're considering a purchase in Montréal, on the Plateau-Mont-Royal, in Rosemont or in Outremont, rates are only one of the things to weigh. Your down payment, your borrowing capacity, your budget and market conditions in the neighbourhood you want are just as important.